
Platforms as gatekeepers: The dangers of walled gardens
Platforms as gatekeepers: The dangers of walled gardens
Platforms as gatekeepers: The dangers of walled gardens
- Author:
- July 26, 2023
Insight highlights
Digital gatekeeping over financial transactions has led to disputes and strategic shifts by traditional payment networks. Platform gatekeeping can worsen social inequalities, heighten cybersecurity risks, and complicate regulations. As such, regulators are exploring increased market fairness and competition through interoperability, possibly aided by blockchain.
Platforms as gatekeepers context
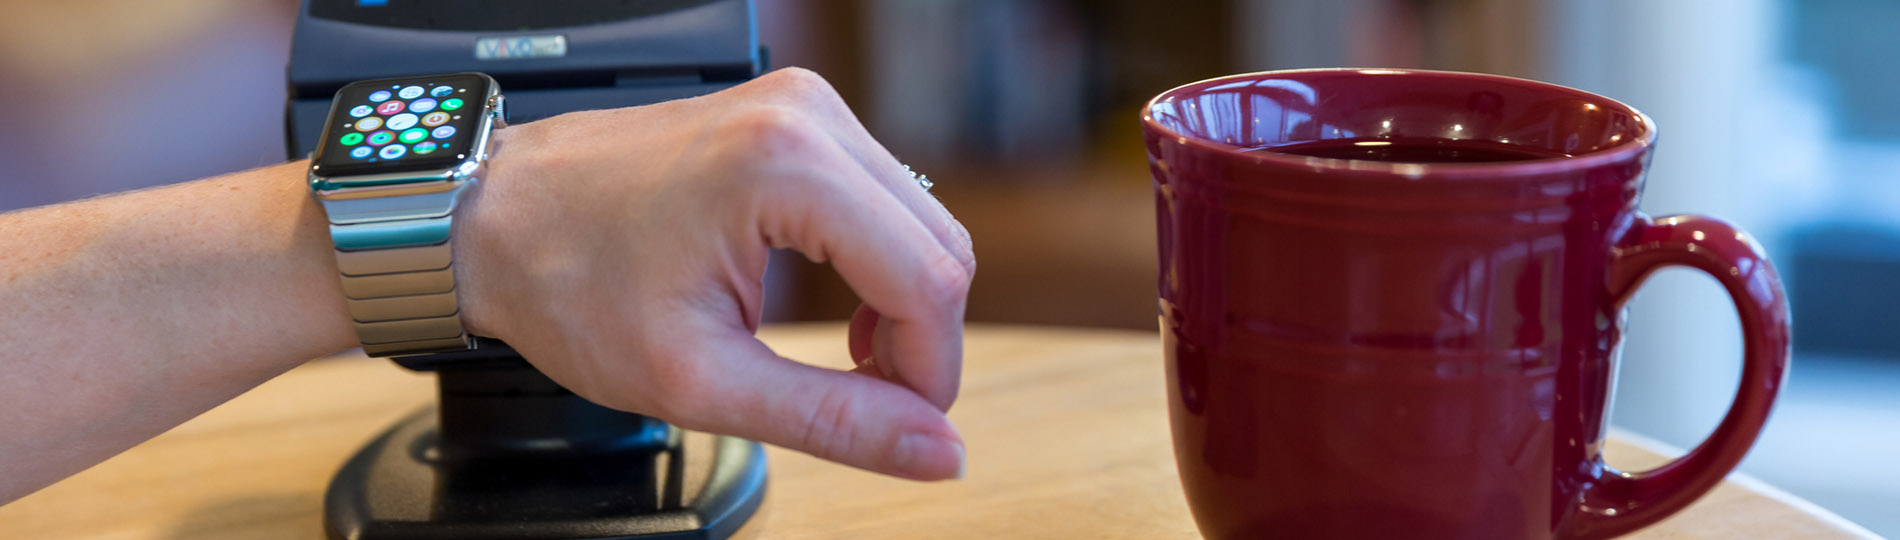
Platforms dominate customer experiences by controlling activities within their ecosystems. This control extends into the payment sector, with examples like Apple, which charges developers up to 30 percent fees on in-app sales, an issue that incited an antitrust battle with Fortnite developer Epic Games. The game developer argued that Apple's prohibition of third-party payment systems is anticompetitive. Despite a 2021 ruling mainly favoring Apple, both parties appealed the decision.
As of October 2022, Apple implemented a rule requiring non-fungible tokens (NFTs) to use its in-app payment services, subject to standard app-related fees. This control has led companies like Visa and MasterCard to shift from a brand preference strategy to a network one, aiming to connect with all potential platforms, such as Venmo, Uber, and WeChat.
However, the control asserted by platform owners, especially those with highly integrated ecosystems like Apple, has its pros and cons. While it can lead to excellent user experiences, such as integrating Apple Pay within iOS, it allows these gatekeepers to set pricing and decide which competitors can access its platform. These powerful entities set the rules within their ecosystems, establishing what is known as "walled gardens." However, there are increasing calls for these platforms to open up, at least partially. Bloomberg reported that Apple is considering accepting external payments in 2023.
Disruptive impact
The European Union (EU)'s Digital Markets Act (DMA) shows its firm stance against anticompetitive practices. If other regulators decide to take action on these walled gardens, the initial step could be the implementation of interoperability. This feature would enable users to securely and compliantly transmit and receive payments with all platforms. Consequently, selecting a provider would become independent of the choices of transaction partners. This development would create a fairer competitive environment, pushing companies to vie for customers based on price, features, privacy, and other quality indicators. Furthermore, this move would empower startups to ensure compatibility with the already established customer base of industry leaders, serving as a leveling force.
Blockchain technology could be integral to this interoperability. Essentially, this technology centers around creating marketplaces without vesting control in a centralized intermediary. This feature makes it a perfect fit for developing open protocols, much like those that underpin the internet, making it challenging for any single entity to alter the rules unilaterally. Participants in such a system can select their providers without concern for compatibility or opt to leave a provider if it introduces unfavorable modifications to pricing, privacy policies, or other conditions.
Moreover, blockchain can keep dominant entities in check. In digital payments, this could mean the difference between a well-established player launching its brand-specific stablecoin versus forming a partnership with multiple stakeholders to jointly design and govern a genuinely open ecosystem.
Implications of platforms as gatekeepers
Wider implications of platforms as gatekeepers may include:
- Financially excluded groups due to lack of identification, access to technology, or a credit history, worsening existing social inequalities.
- Higher fees for users and businesses, decreased competition, and reduced innovation in the sector.
- Some governments leveraging the gatekeeping power of digital payment platforms to survey and control citizen behavior. For instance, a government might pressure a platform to block transactions with political opponents or restrict access to certain services.
- Worsening digital divide, particularly among elderly populations and regions with less technological infrastructure. As society becomes increasingly cashless, these groups could find it harder to participate in economic activities.
- The risk of cyberattacks increasing if the gatekeepers fail to implement adequate cybersecurity measures, resulting in massive data breaches.
- Gig workers relying on digital payments finding it harder to get paid due to limited options and higher fees.
- Domestic economies that rely on global digital payment platforms becoming more vulnerable to foreign policy decisions, sanctions, or conflicts that affect these platforms.
- National laws struggling to adapt to these walled systems, leading to issues around taxation, fraud, and consumer protection.
Questions to consider
- What are some digital payment platforms that you use and why?
- How can governments ensure that these digital platforms remain fair and transparent?
Insight references
The following popular and institutional links were referenced for this insight:
