
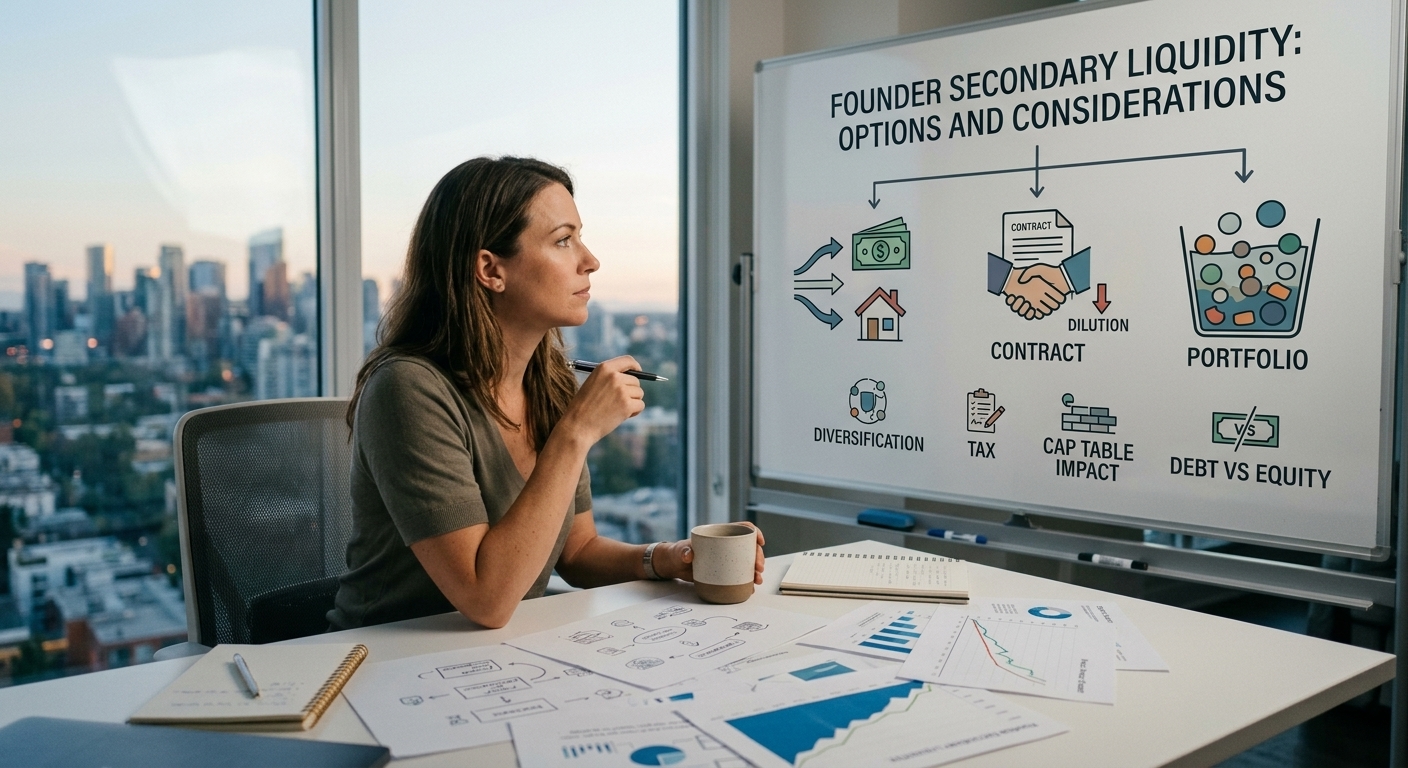
Ask almost any founder of a fast-growing private company what their net worth looks like on paper, and it’s usually a big number attached to shares they can’t actually spend.
That gap between “worth a lot” and “have any cash” is exactly why founder secondary liquidity has become such a bigger conversation over the past few years.
Companies are staying private more than they used to, sometimes a decade or more, and founders are realizing they can’t just wait around for an IPO that might not happen on their timeline, or at all.
Honestly, it’s a strange situation to be in. You’ve built something worth hundreds of millions, maybe more, and you still can’t put a down payment on a house without jumping through a bunch of hoops or taking on personal debt against paper wealth.
Why This Became Such a Big Deal?
There were a few real changes that propelled founder liquidity from being a tangential discussion to an ever-present part of a late-stage cap table discussion.
Companies Just Stay Private Longer Now
Twenty years ago, a hot startup might go public in five or six years. Now it’s routine for companies to stay private for a decade or more, which means founders are sitting on illiquid wealth for way longer than earlier generations of tech leaders ever had to.
- Concentrated risk builds up fast when your entire net worth is one company’s stock.
- Life doesn’t pause for a liquidity event; houses, taxes, and family needs don’t wait for an IPO.
- Founders increasingly want some diversification without having to walk away from the company they’re still building.
Traditional Secondary Sales Come With Real Trade-Offs
A straightforward secondary sale solves the cash problem, but it isn’t free of friction.
- Selling shares outright usually means giving up some ownership and sometimes voting rights too.
- Can trigger a taxable event right away, which the founder may not want to do.
- Time is required to find the right buyer for an appropriate price, and changing the cap table can make it more difficult to raise money in the future.
What Founders Are Actually Looking For?
Before chasing any liquidity option, it helps to get specific about what problem is actually being solved: cash today, diversification, or both.
Match the Option to the Goal
Even with the tax and dilution penalties, a simple secondary sale of a portion of shares could be the clearest path, if the need is just cash in hand.
If the underlying issue is to minimise that exposure to one company’s result but retain ownership and continue to be fully invested in the business, it’s another story altogether and will typically require another type of solution.
Match the Option to the Cap Table Impact
Some approaches change the cap table and require board or investor sign-off. Others are structured specifically to avoid touching the cap table at all, which matters a lot if a founder doesn’t want to complicate a future round or spook existing investors with a big secondary transaction on the books.
Where the Options Actually Differ?
Not every liquidity path solves the same problem, and knowing the rough categories saves a lot of back-and-forth with advisors.
Direct Secondary Sales
A founder sells a slice of shares directly to an investor or through a marketplace. Straightforward, but it means real dilution, a real tax event, and usually a cap table change that everyone involved has to sign off on.
Share-Backed Loans
Using an equity loan rather than a sale. This prevents a need for an immediate tax bite and ensures you retain ownership of the business, but it also introduces debt and the interest payments to it, as well as the terms set by the lender, which can be quite a challenge to calculate for illiquid private shares.
Equity Swap or Pooling Structures
More recent models allow the founders to trade a portion of their shares for a stake in a larger portfolio of other high-growth companies, reducing risk to the foundation across multiple companies rather than just one, without having to sell the founders’ shares or affecting the cap table. It is newer and more selective, and it directly tackles the concentration issue, but not the conversion to cash.
Accumulator runs on this kind of model. Founders keep their vote and their startup’s upside while owning a small piece of a lot of other late-stage businesses. The cash part works differently from a sale, though, because money only comes back when those companies actually exit and it’s split across everyone in the pool. So it’s slow, and the timing and amount aren’t fixed.
Approaching This Without Making a Mess of the Cap Table
Any liquidity move touches other stakeholders, so it’s worth being deliberate rather than reactive.
Loop In the Board Early
Surprising investors with a large secondary transaction rarely goes well. A conversation up front about intent and structure tends to smooth the process considerably compared to presenting it as a done deal.
- Confirm whether the company’s existing agreements even allow secondary transfers.
- Check what right of first refusal or approval steps exist before pursuing anything.
- Be upfront with co-founders about the reasoning; this isn’t a confidence signal issue if it’s handled transparently.
Get the Tax and Legal Picture Straight First
Different structures carry very different tax consequences, and getting this wrong can be expensive.
- Talk to a tax advisor before choosing between a sale, a loan, or a swap structure.
- Understand exactly when a taxable event actually triggers under each option.
- Get real numbers on valuation rather than assuming the last round’s price still applies.
Conclusion
There isn’t one right answer. That’s the whole point. A founder who just needs cash for a near-term expense might be perfectly served by a modest, well-structured secondary sale.
A founder sitting on a huge, concentrated stake who’s worried about single-company risk, but still fully committed to building the business, is solving a different problem, and probably needs a structure built specifically for that instead of a plain sale.
Either way, this isn’t something to figure out alone at 11 pm reading forum posts. Get real advisors involved, understand the trade-offs of each structure, and make the call based on what actually matches your situation rather than whatever option came up first in a conversation with another founder.




