
Quick answer: The health insurance plans for small business owners will buy in 2030 look almost nothing like 2020’s one-size-fits-all group policies. AI quoting, defined-contribution models, and carrier consolidation are pushing the market toward broker-guided, employee-chosen coverage.
Small businesses employ 62.3 million Americans — 45.9% of the US workforce, according to the SBA’s 2025 Small Business Profile.
How this cohort buys health coverage over the next five years will reshape the entire US insurance economy.
Shift 1: AI shortlists, humans decide
By 2028, nearly every quoting platform will have AI at the intake layer. It compresses plan comparison from two weeks to under an hour.
But the 2025 KFF Employer Health Benefits Survey — which pegged the average family premium at $26,993 — shows small firms face sharper renewal volatility than large employers.
Renewal negotiation is still a human-to-human activity. That is why licensed broker demand is rising alongside AI adoption, not despite it.
Shift 2: Defined contribution goes mainstream
ICHRA and QSEHRA adoption is accelerating. Instead of choosing a group plan, owners fund a monthly allowance, and employees choose individual coverage.
This eliminates the “wrong plan for half the workforce” problem that plagues traditional group policies.
Shift 3: Carrier consolidation tightens network design
Cigna, Humana, Aetna, BCBS, and UnitedHealthcare continue absorbing regional carriers. Fewer logos, but plan-document language diverges sharply between states.
A broker fluent in all five carriers’ network quirks catches mental-health parity gaps and formulary omissions that no search tool surfaces.
Shift 4: Specialty drugs reshape premium math
GLP-1 coverage decisions alone are shifting full-population premium curves. Health Affairs analysis showed large employers materially expanded weight-loss drug coverage in 2025, and that pressure is now reaching small-group plans.
Owners who don’t model formulary impact at the plan-design stage walk into 8-12% renewal jumps they didn’t budget for. The owners who hold pricing are the ones whose brokers flagged the exposure during underwriting.
Shift 5: Local broker networks become force multipliers
Multi-carrier brokerages with long-standing carrier relationships are outperforming national online agencies in claim denial resolution and renewal stability. The reason is relational, not digital — regional underwriters return a familiar broker’s email the same day.
Firms like Custom Health Plans, which have worked directly with the five major carriers for 30+ years, show how local depth beats national reach for small employers.
Shift 6: The broker-cost myth dies
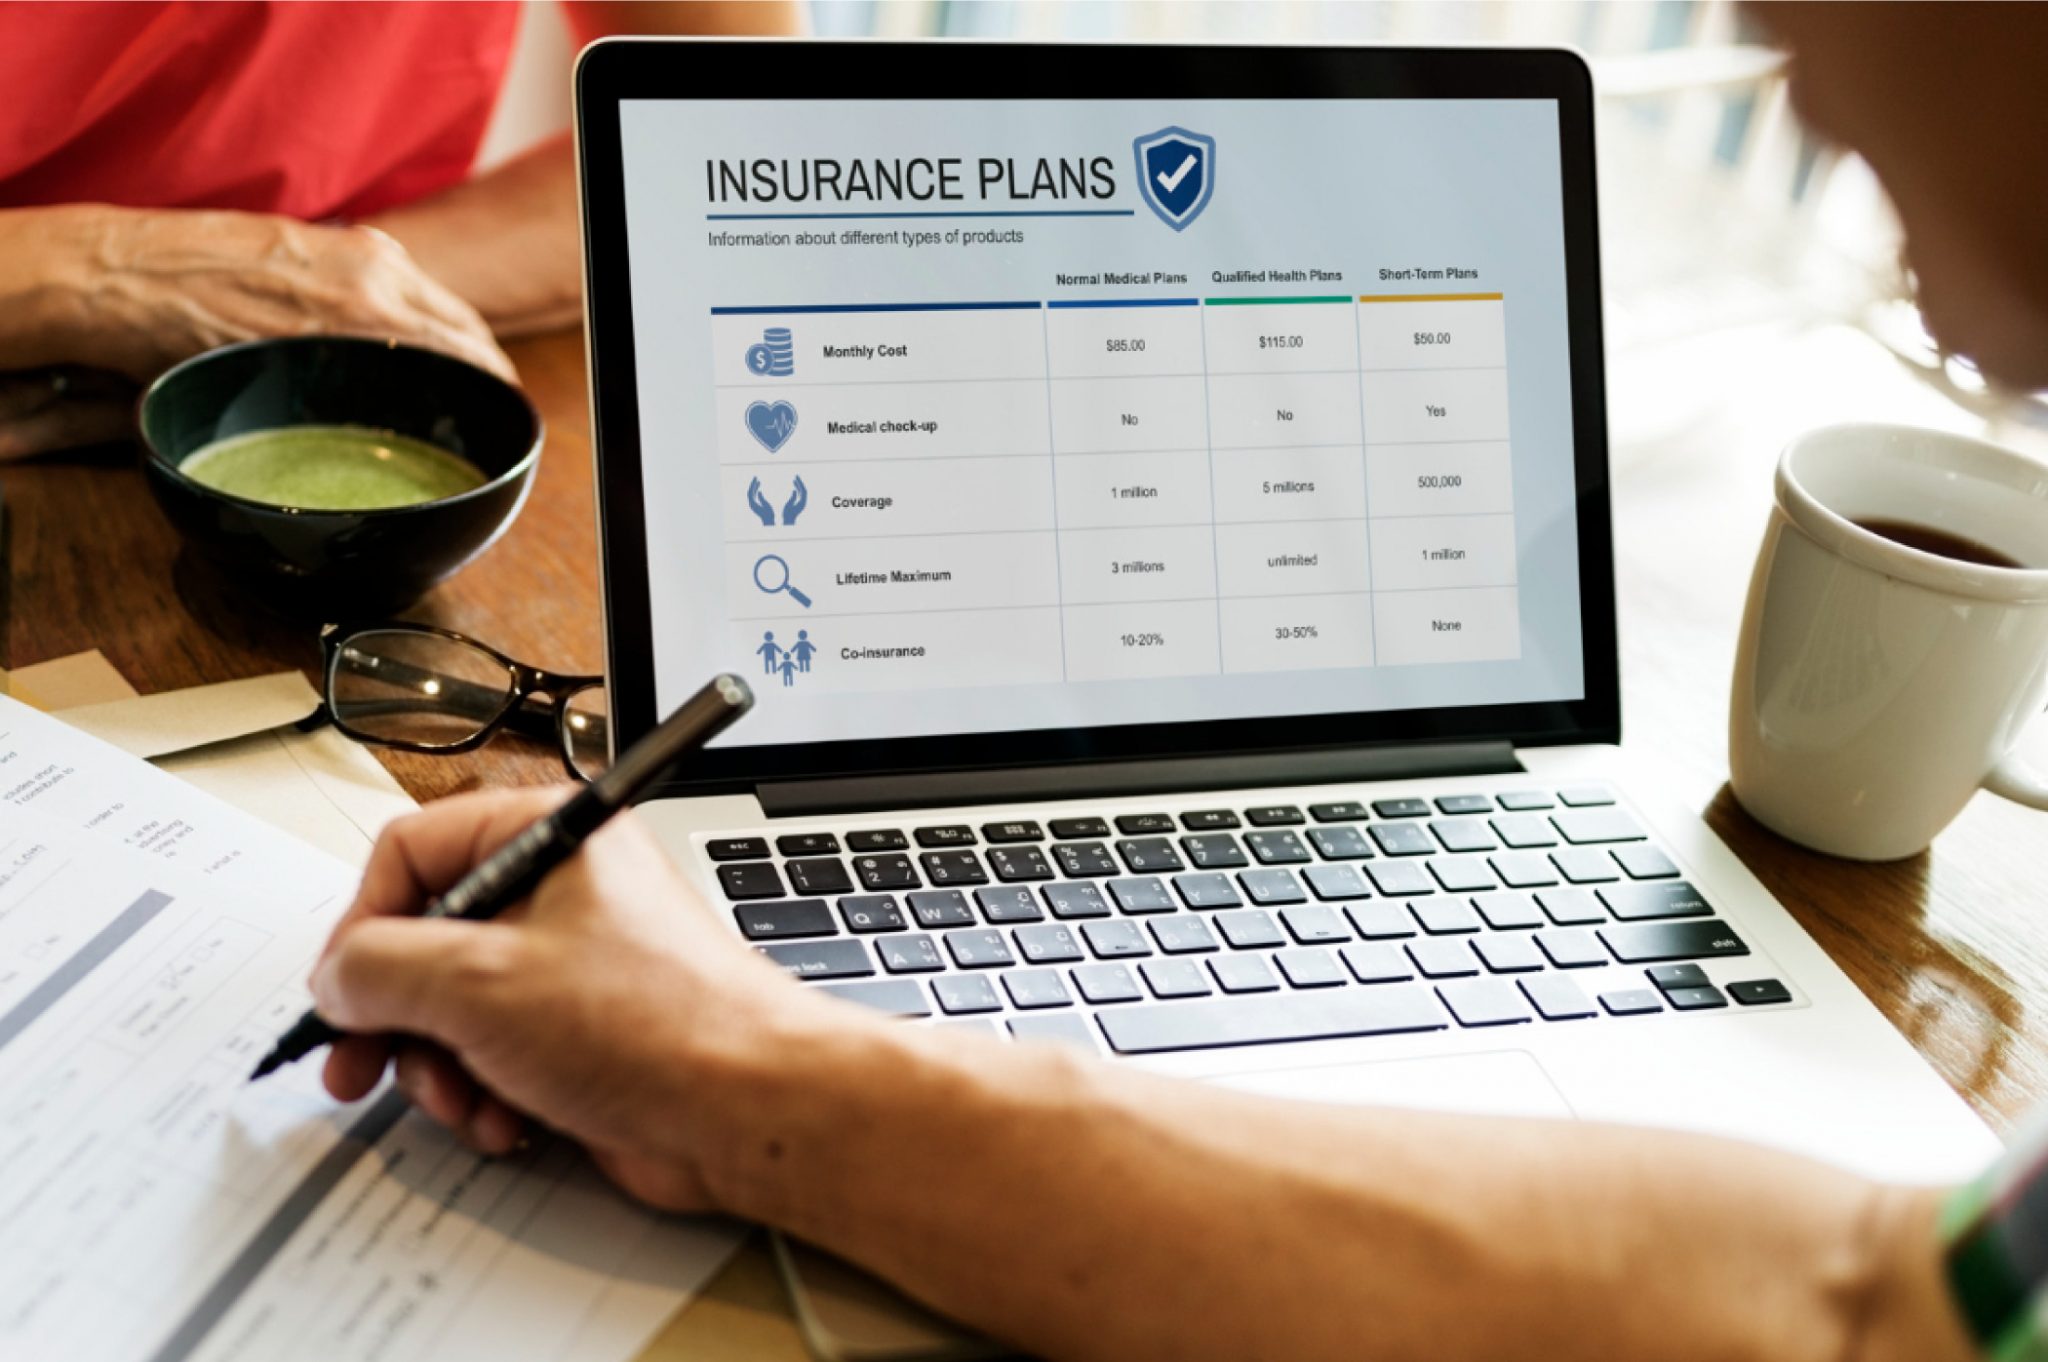
Owners are realizing brokers cost them nothing extra. Carriers pay broker commissions, not the employer. The premium is identical through a broker or direct — the only difference is expertise and advocacy at claim time.
This recognition is accelerating the shift toward advisor-led small business health insurance procurement across every state and industry.
The 2030 picture
AI will handle discovery. Licensed brokers will handle decisions. Group plans will look more like curated individual coverage.
Owners who master this blend will spend less per covered life than competitors relying on a single channel.




